Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
At sixteen, I turned $200 of birthday money into a pair of sneakers I wore exactly four times before they went out of style. That same $200, dropped into an index fund instead, would be worth noticeably more today and it wouldn’t be sitting in the back of my closet smelling faintly of regret. Was I financially reckless? A little. Was I also completely normal for a teenager? Also yes.
Most lists of investment tips for teens assume you already have a job, a bank account, and zero interest in sneakers. This one doesn’t. If you’re still figuring out how to make money as a kid in the first place, start there, everything below assumes you’ve got at least a little cash coming in and want to stop it from evaporating into things you’ll regret by junior year.
Here’s the thing nobody tells you: the fact that you’re a teenager thinking about investing tips for teenagers at all already puts you ahead of most adults, who don’t start until their late twenties or thirties. You don’t need a trust fund, a suit, or a Bloomberg terminal. You need a plan, a little patience, and because this is technically your first legal hurdle a parent or guardian willing to co-sign a form.
So what actually works? I asked people who do this for a living instead of just guessing.
Short answer: yes, but not entirely on your own, with one exception. Most brokerages won’t let anyone under 18 open a standard account, which is why custodial accounts (UGMA/UTMA) exist: an adult opens and legally controls the account, but the money belongs to you. The catch is that the custodian, usually a parent makes the investing decisions, not you.
The Fidelity Youth Account works differently. It’s marketed as the only brokerage account teens 13–17 can own and control themselves, letting them place trades with as little as $1 using fractional shares, while a parent retains oversight, they approve the account and can close it, but they can’t trade or withdraw funds. Apps like Greenlight Invest+ and Acorns Early sit somewhere in between, functioning like custodial accounts even when they’re not formally branded as UGMA/UTMA.
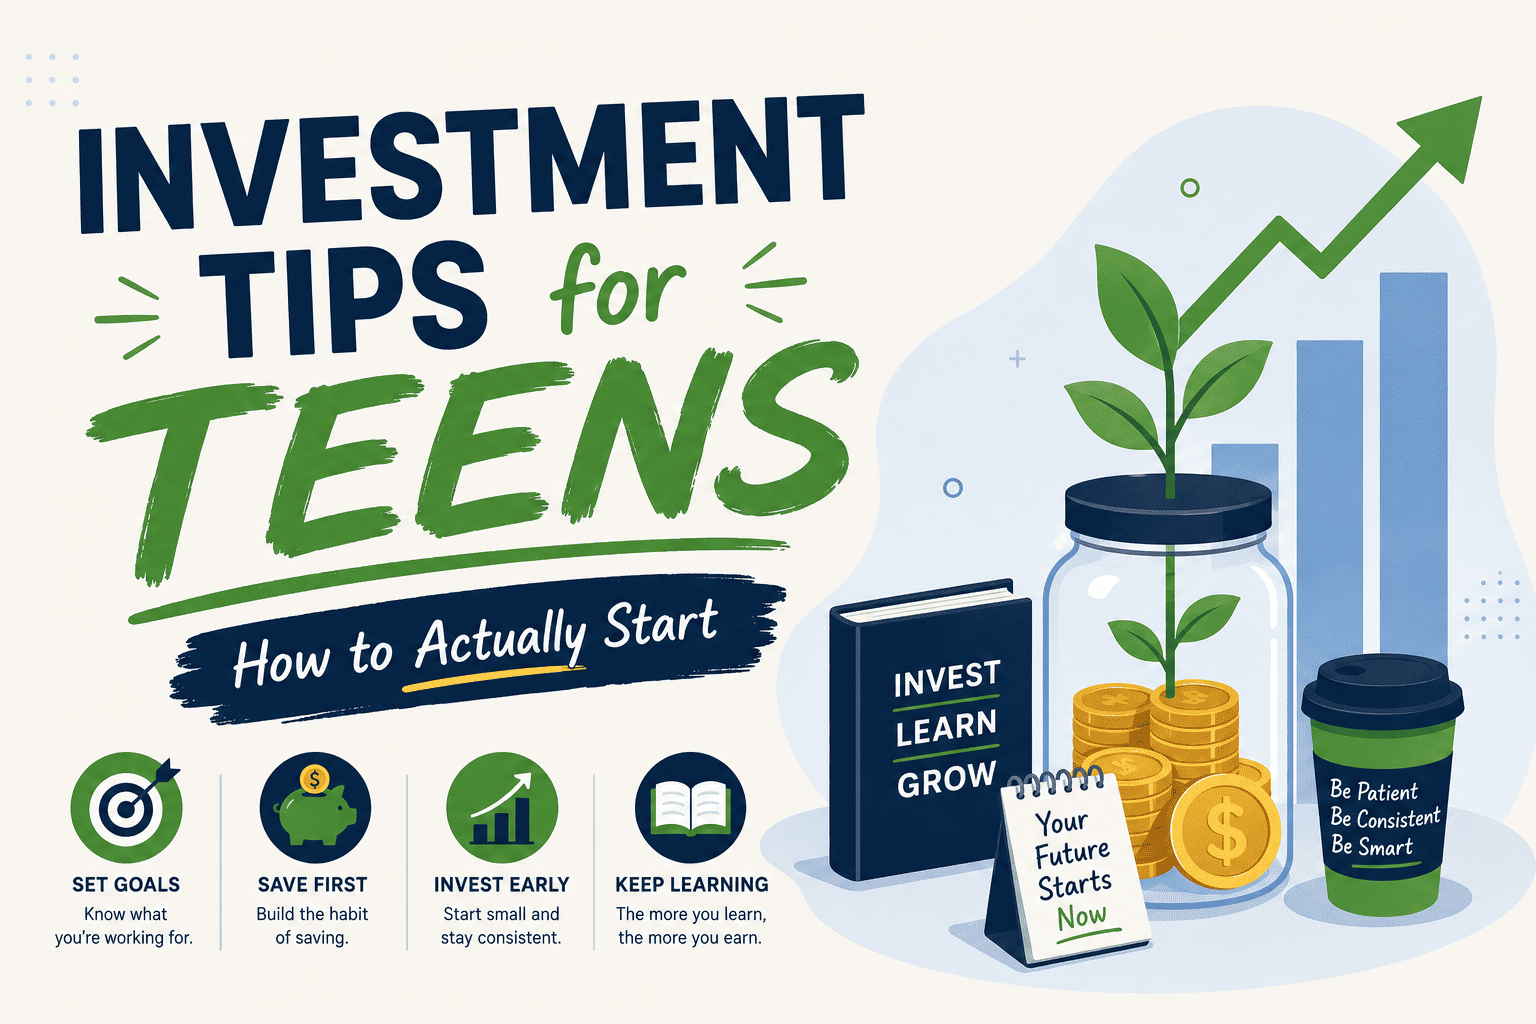
You don’t need $5,000 to begin. Fractional shares mean $10 or $20 a month buys you a genuine slice of a real company or fund. What matters isn’t the size of your first deposit, it’s how many years that money has to grow before you need it. A dollar invested at 16 has roughly a decade’s head start on the same dollar invested at 26.
Do you have earned income from a summer job? A custodial Roth IRA is usually the strongest option, since decades of tax-free growth start the moment the money goes in. Saving generally, with no specific target? A UGMA/UTMA or a Fidelity Youth Account gives you flexibility. Saving for college specifically? That’s a 529 plan’s job, not a brokerage account’s, different tool, different tax treatment.
Individual stocks feel exciting, a single company you believe in, watching the ticker move. Index funds are boring by design: they spread your money across hundreds of companies at once, which is exactly why they’re the more forgiving place to learn. Boring, in investing, is usually a compliment.
Set up a recurring transfer, even $10 a week, so the decision to invest only happens once. Every future contribution becomes automatic, which matters because “I’ll invest what’s left over” almost always turns into “there was nothing left over.”
It’s tempting to go all-in on whatever’s trending in your group chat. Resist it. A handful of index funds spread across different sectors will outlast almost any single “sure thing,” mostly because there’s no such thing as a sure thing.
Markets go down before they go up, sometimes for uncomfortably long stretches. Money you’ll need in the next year or two (for a car, a trip, a phone) belongs in a savings account, not a brokerage account. Investing is a long game; don’t force it to double as your emergency fund.
Teenagers are an increasingly common target for what regulators call “relationship investment scams”- someone builds trust with you online, often through social media or a group chat, before steering you toward a fraudulent platform. The SEC’s investor education office flags this specifically as a rising risk. If a stranger online is enthusiastic about your financial future and light on verifiable credentials, that’s the whole warning sign, no need to overthink it further.
Look at your portfolio monthly, not hourly. Checking a long-term investment every day mostly teaches you to panic over normal, meaningless fluctuations- and panic is what turns a temporary dip into a permanent loss, because it tempts you to sell at exactly the wrong moment.
The real value of starting now isn’t the dollar amount, it’s the years of practice reading a portfolio, riding out a dip without panic-selling, and understanding what you actually own.
This is the part parents ask about more than teens do, but it’s worth knowing. Custodial (UGMA/UTMA) accounts trigger what’s known as the “kiddie tax”: for 2026, the first $1,350 of investment earnings is tax-free, the next tier is taxed at your rate, and above that it’s taxed at your parent’s rate. It’s not something to lose sleep over at $20-a-month investing levels, but it’s one more reason to talk to a parent or guardian before opening an account rather than after.
Probably: but with realistic expectations. Nobody turns $200 into a fortune by graduation. What you’re really building in these years isn’t a large balance; it’s a habit, and habits compound just as reliably as money does. Wish someone had told sneaker-buying, sixteen-year-old me that.
This article is for educational purposes and isn’t personalized financial advice, talk to a parent, guardian, or financial professional before opening any investment account.